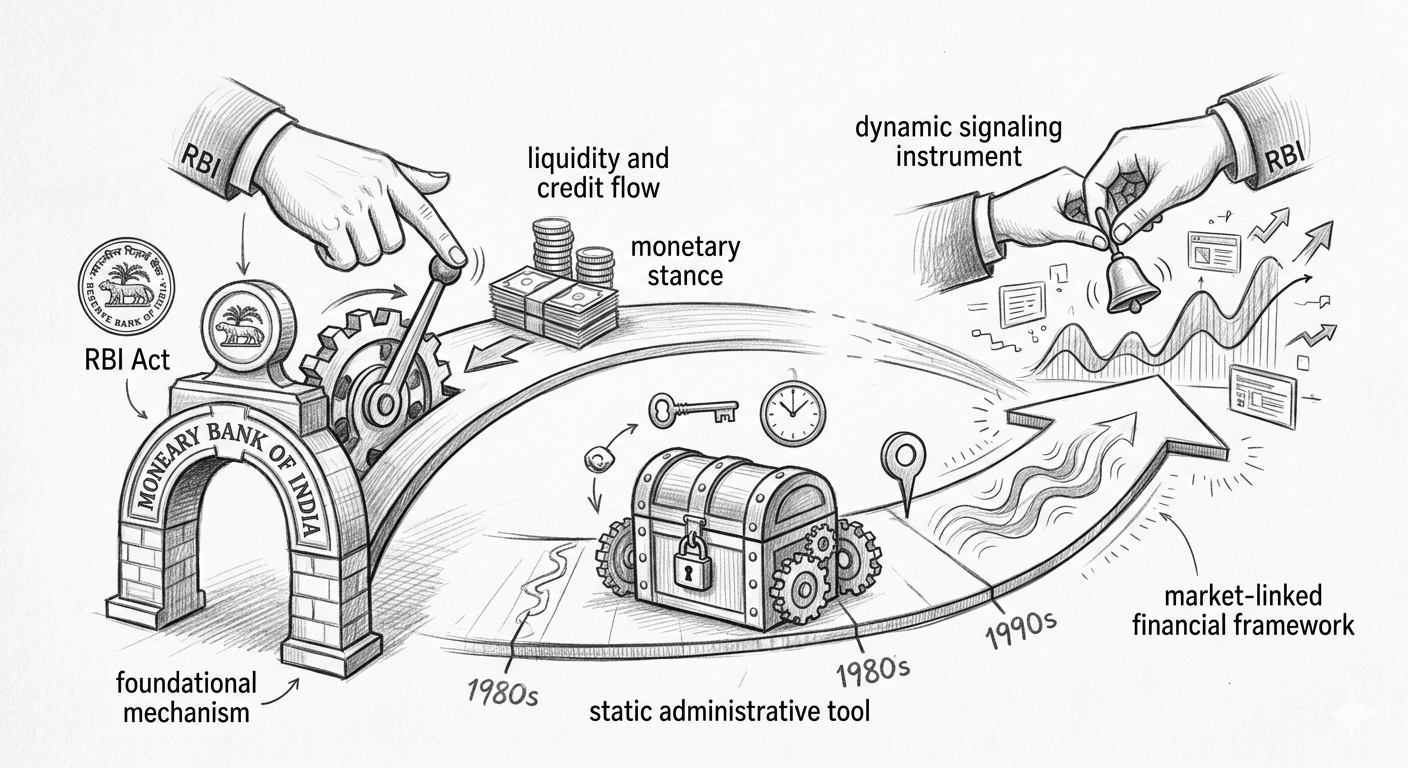
The Bank Rate Policy in India serves as the foundational mechanism for monetary regulation. It acts as the primary tool through which the Reserve Bank of India (RBI) manages liquidity and credit flow. Established under the RBI Act, this rate sets the cost of long-term borrowing and rediscounting for commercial banks, showing the central bank's overall policy stance. Its transition from a fixed administrative rate in the to a dynamic market signaling tool in the reflects India's shift toward a market-linked financial system that maintains economic stability.
🎯 In this chapter, you will understand:
- The legal and technical definition of the bank rate under the RBI Act.
- How the bank rate remained fixed during the as an administrative benchmark.
- The reactivation of the bank rate as an active signaling instrument during the financial reforms.
- The modern economic role of the bank rate as a baseline for penal interest rates and long-term liquidity control in .
💡 Why this topic matters: The bank rate sets the baseline cost of long-term funds in the economy and penal charges for banks failing reserve requirements, directly influencing bank lending behavior.
🧠 Core Idea: Adjusting the bank rate allows the central bank to guide long-term credit availability, control inflation, and maintain financial stability across commercial banks.
The Narrative of Monetary Control: Defining the Bank Rate
The Indian financial system relies on regulatory standards to balance credit growth across the economy. Within this structure, the central bank uses long-term discount windows to communicate its credit policies to scheduled commercial banks across the country.
Defining the Core Regulatory Instrument
In Indian banking, the bank rate is defined in the RBI Act. The Bank Rate is the standard rate at which the Reserve Bank of India (RBI) buys or rediscounts bills of exchange or other commercial paper eligible for purchase under the Act:
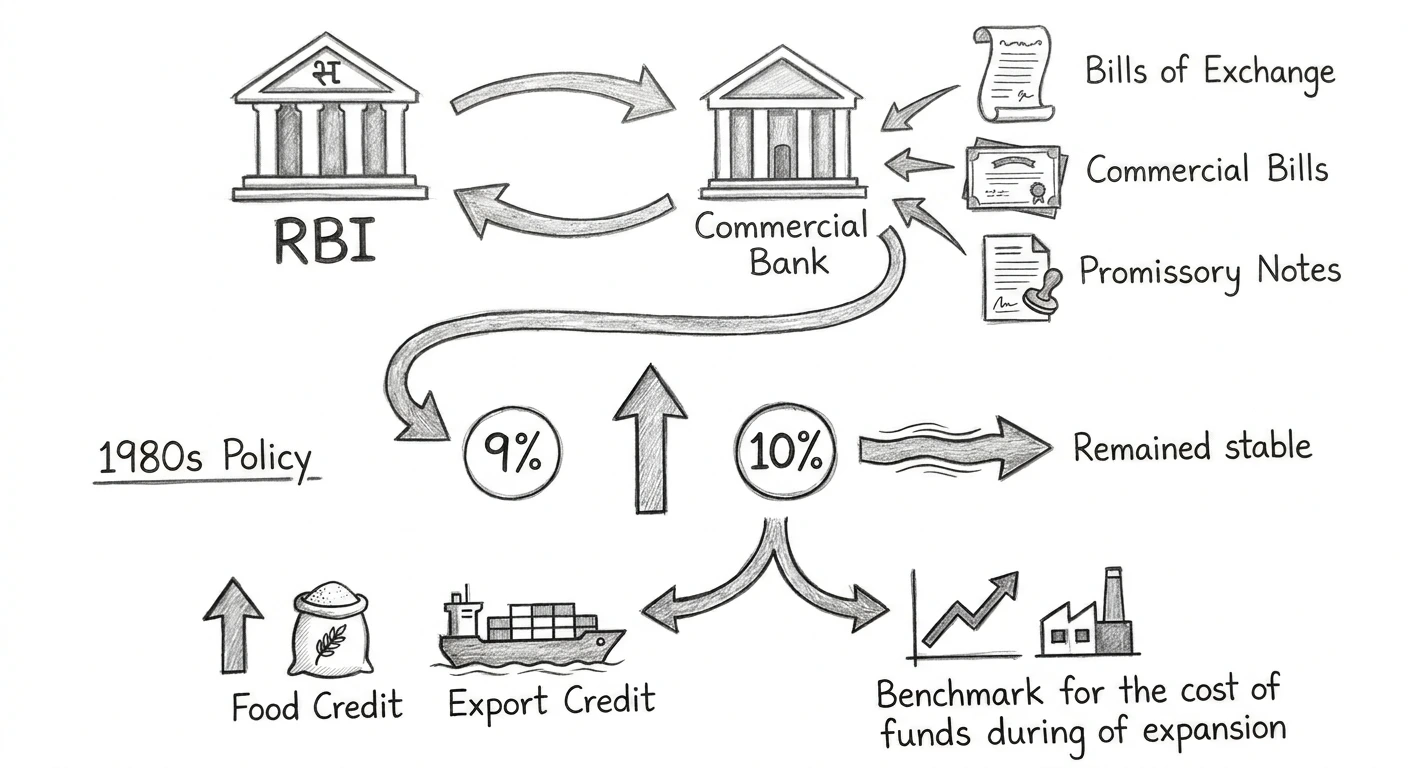
Bank rate and other monetary tools - (i) Bills of Exchange – Written agreements where one party commits to pay a fixed sum to another on a specific future date.
- (ii) Commercial Bills – Short-term credit paper used to settle trade and commercial dealings.
- (iii)
Promissory Notes and Debt Instruments
Written agreements promising to pay a fixed amount on demand or at a set future date.
- (a) RBI-approved short-term debt paper used by commercial banks.
- (b) State government development loans used for liquidity facilities.
- (c) Long-term rediscounted institutional bills.
- (d) Export and priority sector refinance bills eligible under central bank rules.
This statutory role makes the RBI the lender of last resort for commercial institutions. The Chakravarty Committee Report highlighted its importance, showing that the central bank could guide commercial bank lending and national credit trends by adjusting this rate.
Analyzing the Bank Rate Policy During the 1980s
Before economic opening, monetary regulation relied heavily on direct administrative control rather than market forces. Policy tools were kept stable to give public sector financial channels predictable borrowing costs over extended periods.
- Direct credit distribution mechanisms guided credit flow to target economic sectors.
The Era of Regulatory Stability and Committee Insights
During the , India operated under fixed interest rates where the bank rate acted as a stable benchmark. A major policy change occurred in , when the bank rate was raised from 9% to 10%. This move triggered an increase in refinance rates for food supply and export credit facilities. Despite recommendations from the Chakravarty Committee to use the rate more actively, the policy stayed steady. The bank rate remained fixed at 10% throughout the late , until the economic reforms of .
- (i) Interest rates on RBI credit to commercial banks were tied directly to the bank rate.
- (ii) The rate served as a fixed cost benchmark during a period of state-guided industrial expansion.
- (iii) Refinance limits were set based on administrative targets rather than daily market liquidity.
- (iv) Market interest rates had minimal impact on central bank lending decisions during this period.
The Great Reactivation: Developments in the 1990s Reform Era
Opening up the Indian economy required a redesign of standard monetary tools. As direct administrative rules gave way to market-driven treasury management, older policy channels were updated to keep pace with changing market conditions.
- Market-determined interest rates replaced administered interest structures across commercial sectors.
Strategic Repositioning as a Monetary Signaling Tool
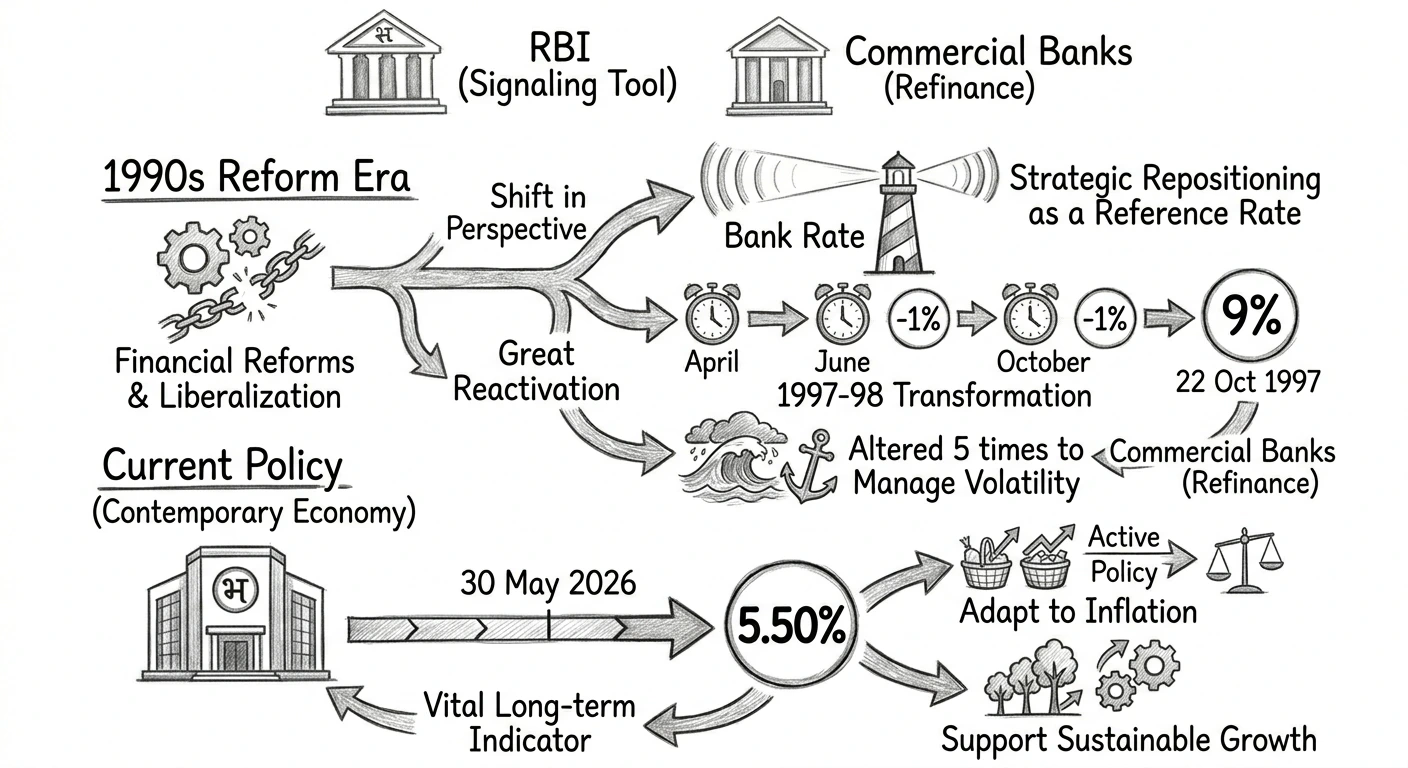
During the early financial reforms, the bank rate saw limited use as newer policy instruments were introduced. However, as economic liberalization continued, the system required stronger monetary signals. By the , the RBI reactivated the bank rate as an active reference rate for the financial system. During , the rate was adjusted to reflect real-time market liquidity. To support an easing credit environment, the RBI cut the rate by 1% three times during , , and , bringing it down to 9% per annum by .
Bank rate impact decision flowchart - Policy Revisions: The bank rate was modified five times during to handle financial market volatility under monetary signaling.
- Refinance Benchmark: It became the baseline rate for central bank credit facilities extended to commercial banks.
- Market Alignment: Linkages were created between commercial interest rates and central bank signals.
- Regulatory Reforms: Guidelines under the Narasimham Committee Reports helped transition monetary management toward market-based controls.
⚡ Quick Revision Capsule: Bank Rate Key Parameters
The following table outlines the main structural features, historical trends, and practical functions of the Bank Rate Policy in India:
| Parameter / Feature | Historical & Policy Detail | Operational Function |
|---|---|---|
| Governing Statute | Enacted under Section 49 of the RBI Act | Defines standard conditions for rediscounting commercial bills and debt paper. |
| 1980s Status | Raised from 9% to 10% in | Served as a stable administrative benchmark rate for a decade. |
| 1990s Reform Shift | Reactivated as a reference rate in | Adjusted five times in one fiscal year to signal policy changes. |
| Current Standing (2026) | Stands at 5.50% in | Acts as an institutional signal for long-term borrowing costs. |
| Penal Mechanism | Applied when banks fail statutory reserves under Banking Regulation Act rules | Calculated as a fixed penalty percentage above the bank rate for CRR/SLR defaults. |
📝 Summary
The Bank Rate Policy in India has evolved from a fixed administrative setting in the into a key signaling mechanism within the modern financial framework. Defined under the RBI Act, it governs long-term borrowing conditions and sets penalties for statutory reserve shortfalls. During the reform phase of , its reactivation helped move the economy toward flexible, market-linked monetary control. In , with the bank rate standing at 5.50%, it remains an essential tool for communicating long-term policy goals alongside short-term instruments like the repo rate.
🚀 Quick Revision Points
Essential facts to review before examinations:
- (i) The rate is statutorily governed under the provisions of the RBI Act for rediscounting eligible commercial paper.
- (ii) It reached an administrative fixed level of 10% in , staying at that level for a decade.
- (iii) The instrument was reactivated as a flexible reference rate during the monetary reforms of .
- (iv) It serves as the baseline yardstick for computing penal interest rates on commercial banks that fail reserve requirements.
- 💡 Exam Tip: Always distinguish between the Bank Rate (long-term, collateral-free rediscounting and penalty benchmark) and the Repo Rate (short-term, collateral-backed liquidity facility) when answering monetary policy questions in competitive exams.
❓ Frequently Asked Questions (FAQ)
Q1: How does the Bank Rate differ from short-term liquidity tools like Repo Rate?
A1: The Bank Rate deals primarily with long-term borrowing and rediscounting commercial paper without collateral under the RBI Act. In contrast, the Repo Rate manages short-term daily liquidity backed by government securities.Q2: What major shift did the bank rate undergo during the fiscal phase of 1997-98?
A2: The rate shifted from a fixed administrative anchor to an active market signaling tool. It was revised five times in a single fiscal year, including three cuts that brought it to 9% in .Q3: What role does the Bank Rate play in penalizing commercial banking entities today?
A3: It serves as the benchmark for calculating penal interest. If scheduled banks fall short of their mandated cash reserve ratio (CRR) or statutory liquidity ratio (SLR) requirements under Banking Regulation Act guidelines, fines are charged at set percentage points above the bank rate.