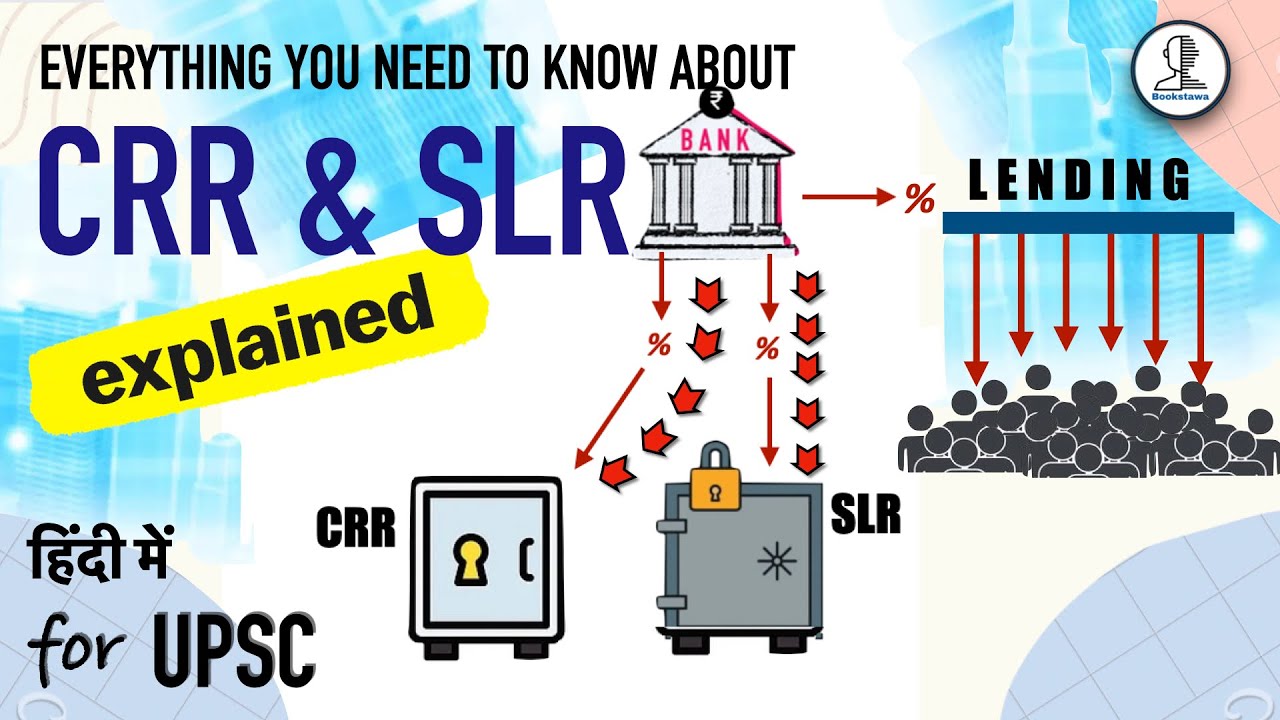
The Cash Reserve Ratio (CRR) is a main tool in India's financial system. The Reserve Bank of India (RBI) uses it to control cash flow and money supply. During the and , the RBI used it to balance government budget shortages and foreign money coming into the country. By asking banks to keep a set part of their demand and time liabilities as cash, the RBI makes sure the banking system stays safe with a strong safety buffer while keeping price inflation under control.
🎯 In this chapter, you will understand:
- What the Cash Reserve Ratio (CRR) is and how it works.
- The legal basis of CRR under the Reserve Bank of India Act.
- How CRR was used in the and to handle liquidity.
- The effect of CRR changes on bank loans and total money supply.
💡 Why this topic matters: Knowing CRR helps us see how central banks keep commercial banks safe and control inflation across the country.
🧠 Core Idea: CRR forces banks to store a fixed portion of their deposits as cash with the RBI, directly changing how much money is available for lending.
📌 Cash Reserve Ratio (CRR) in India: Role and Trends
The rules for cash reserves keep banks financially healthy. By watching these stored reserves, policy leaders can guide overall economic stability.
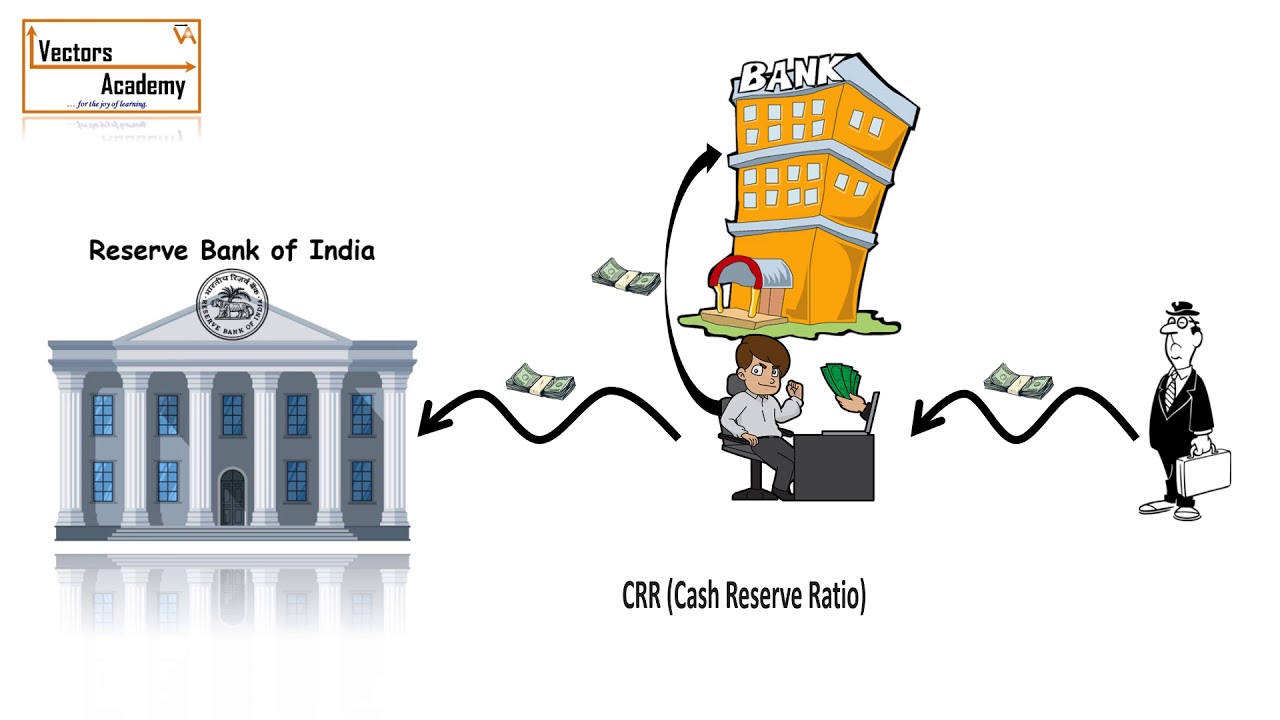
The term Cash Reserve Ratio (CRR) means the exact share of cash that commercial banks must keep with the Reserve Bank of India (RBI). This amount is calculated as a percentage of their total demand and time liabilities. It serves as a first guard in money control, preventing banks from lending too much and keeping the financial system safe and strong.

Cash Reserve Ratio (CRR) explained Definition and Legal Basis of the Cash Reserve Ratio
The rules for CRR come from law. This gives the central bank clear power to shift cash reserve levels as the economy changes.
Operational Mandates under the Reserve Bank of India Act
Under the Reserve Bank of India Act, commercial banks must keep an average daily cash reserve equal to at least three percent of their total demand and time liabilities, based on figures from the . The RBI can change this rate between 3% and 15% depending on economic needs.
- (i) Statutory Reserve: The basic 3% required by law.
- (ii) Incremental Reserves: Extra reserves added during sudden jumps in deposits.

📌 Policy Use of CRR During the 1980s and 1990s
The and were important years when CRR was used as a regular tool to handle cash flow problems. Starting in , the RBI raised the ratio from 9% to 9.5% on , to pull out extra cash without cutting off loans to essential businesses.
Detailed Analysis of 1991 and 1994 Monetary Shifts
In , the Narasimham Committee noted that CRR was helpful for monetary control but suggested lowering it slowly over time. However, in , a 10% incremental CRR was brought in to handle economic troubles. Later in , the rate was raised in steps from 14% to 15% because of high government deficits and rising foreign currency reserves, as announced on .
- (i) A step-by-step reduction in lowered the rate by 4 full percentage points.
- (ii) Changes were often made to balance out growing foreign exchange reserves.
📌 Impact of CRR on Banking Operations and Money Supply
The CRR acts as a direct lever to remove or inject cash available for loans in the banking system. During the , reserve rates stayed high, showing a time of strict money rules aimed at checking the overall money supply.
Mechanisms of Credit Contraction and Profitability Impacts
When the RBI raises the CRR, banks must lock away a larger part of their deposits. This directly lowers the amount of money open for business loans. Less lending shrinks the overall money supply and can lower bank profits. On the flip side, lowering the ratio gives banks a quick boost in cash, helping them lend more when the economy moves slowly.

Policy wheel and banking operations
⚡ Quick Revision Capsule: Macroeconomic Indicators
This reference dashboard outlines the key monetary rates used by the central bank to manage market liquidity:
| Monetary Policy Tool Instrument | Current Operational Rate Value | Primary Functional Role |
|---|---|---|
| Statutory Liquidity Ratio (SLR) | 18.00% | Mandatory investment in approved liquid government securities. |
| Cash Reserve Ratio (CRR) | 3.00% | Direct cash reserves held with the central bank without interest. |
| Benchmark Repo Rate | 5.50% | Rate at which the central bank lends short-term money to commercial banks. |
| Reverse Repo Rate | 3.35% | Rate at which the central bank borrows short-term funds from commercial banks. |
| Bank Rate & MSF | 5.50% | Standard penalty rate and marginal standing facility rate for emergency liquidity. |
📝 Summary
The Cash Reserve Ratio is an essential safety pillar for economic balance in India. By changing the percentage of deposits that banks must keep as cash, the Reserve Bank of India manages the overall money supply and controls inflation expectations. From high reserve levels during the peak of 15% to today's baseline of 3.00%, the path of CRR shows India's growth toward a open and flexible banking system while keeping the statutory safety rules intact.
🚀 Quick Revision Points
Essential facts to review before examinations:
- (i) The CRR marks the exact share of cash deposits that commercial banks must keep stored with the central bank.
- (ii) The main legal mandate comes from Section 42(1) of the Reserve Bank of India Act.
- (iii) The historical peak for CRR reached 15% in to fight high inflation and deficits.
- (iv) Current policy uses a 3.00% base rate along with key policy rates like the Repo rate to keep credit flowing smoothly.
- 💡 Exam Tip: Remember that banks do not earn any interest on the funds kept with the RBI under CRR requirements.
❓ Frequently Asked Questions (FAQ)
Q1: Does the Reserve Bank of India offer interest earnings on standard CRR balances?
A1: No, the RBI pays zero interest on cash balances kept by commercial banks under the CRR requirement, making it a non-earning cash reserve.Q2: What forms the core base for calculating CRR obligations?
A2: CRR reserves are calculated against the total Net Demand and Time Liabilities (NDTL) recorded at the end of operations on the .Q3: How does adjusting reserve levels modulate systemic consumer inflation?
A3: Raising CRR locks up excess money in banks, reducing loans available to the public. This drop in credit slows down spending and helps stabilize rising market prices.