The Statutory Liquidity Ratio (SLR) stands as a cornerstone of Indian monetary policy, functioning as a vital instrument used by the Reserve Bank of India (RBI) to ensure financial discipline. Historically, its significance peaked during the , serving as a dual-purpose tool: it managed inflationary pressures by restricting the lending capacity of commercial banks while simultaneously securing a guaranteed market for government securities. By mandating that banks maintain a specific portion of their Net Demand and Time Liabilities (NDTL) in safe, liquid forms, the SLR framework provided the institutional stability necessary for the nation's fiscal expansion and public sector financing during critical developmental decades.
🎯 In this chapter, you will understand:
- The core definition and functions of Statutory Liquidity Ratio (SLR) in Indian banking.
- The difference between SLR and Cash Reserve Ratio (CRR) in reserve management.
- Historical shifts in SLR rates throughout the 1980s, 1990s, and present day.
- How SLR controls credit flow, ensures bank solvency, and supports government borrowing.
💡 Why this topic matters: SLR is a foundational tool of monetary policy that regulates how much money banks can lend and ensures they keep enough safe assets to protect depositors.
🧠 Core Idea: Banks must set aside a mandatory percentage of their deposits in safe assets like cash, gold, or government bonds before giving out loans to the public.
The Narrative of Financial Stability: Defining SLR in India
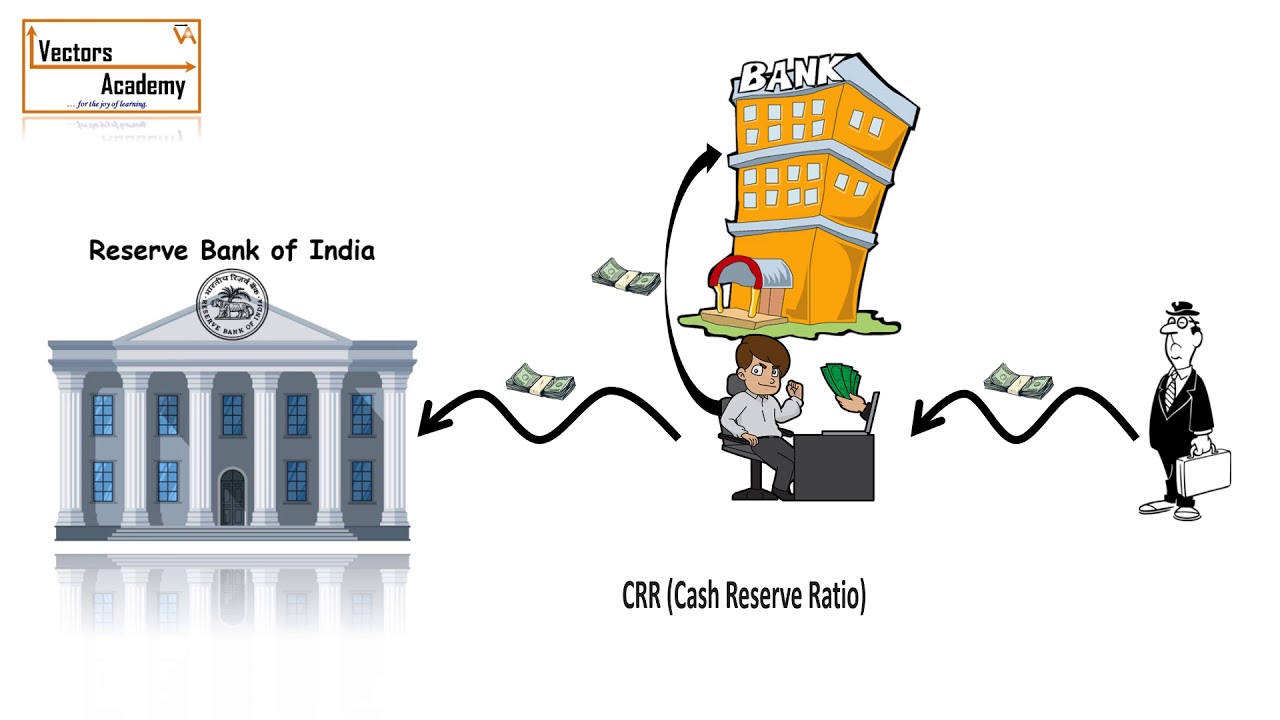
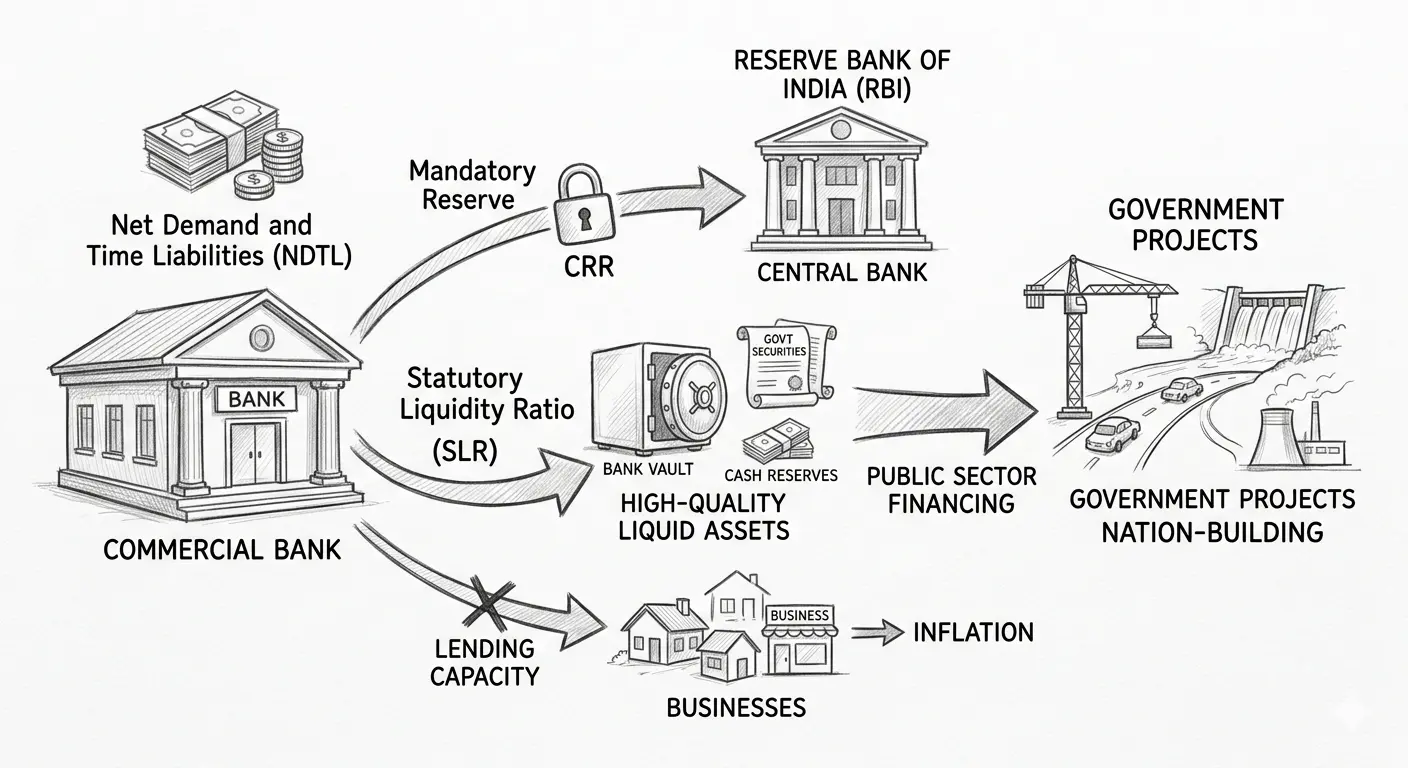
In the complex landscape of Indian Central Banking, the SLR acts as a mandatory buffer. Unlike the Cash Reserve Ratio (CRR), which deals strictly with cash kept with the RBI, the Statutory Liquidity Ratio requires banks to maintain a reserve of high-quality liquid assets within their own vaults. This narrative of prudence and liquidity ensures that even in times of economic stress, banks possess the solvency to meet depositor demands while funneling capital into nation-building projects through approved securities.
Analyze the Definition and Core Functions of SLR
The technical ratio between liquid assets and the demand and time liabilities held by Indian banks is formally defined as the Statutory Liquidity Ratio. It serves as a regulatory valve for the entire economy.
Explore the Mechanics of Liquid Assets and Bank Liabilities
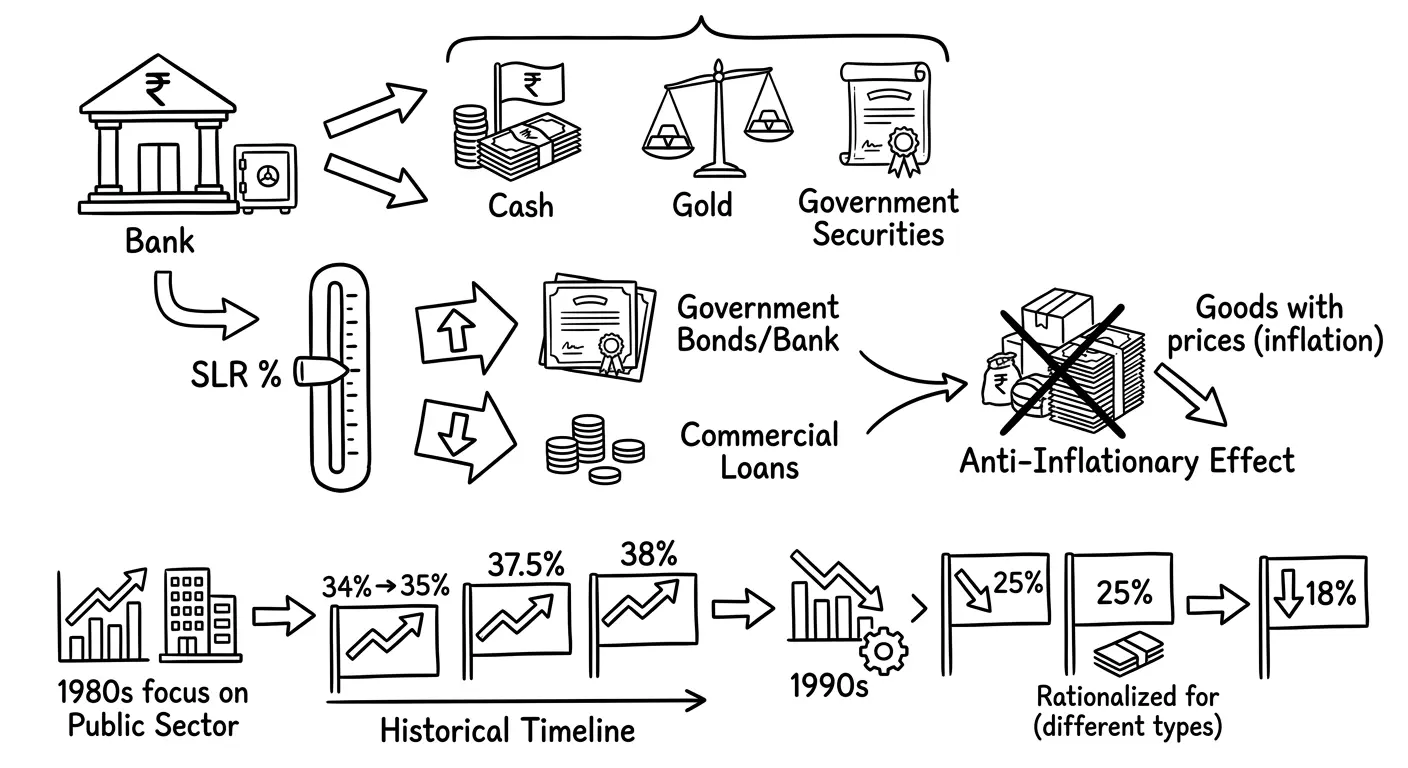
Under the statutory mandate, banks must divert a portion of their resources away from commercial lending. This categorization of liquid assets includes gold, physical cash, and government-approved securities. When the RBI enforces a higher SLR, it intentionally reduces the loanable funds available to the private sector, creating a powerful anti-inflationary effect. Furthermore, this mechanism influences public sector financing by directing bank capital toward state-backed debt instruments.
- (i) Liquid assets provide an immediate safety net for bank depositors.
- (ii) Mandatory investments in securities ensure fiscal stability for the government.
Deep Dive into SLR Policy Adjustments During the 1980s and 1990s
The represented a period of active liquidity regulation. The RBI utilized the SLR extensively to support public sector investment goals without the inflationary risk of printing new reserve money.
Chronicle of Historical Rate Changes and Statutory Mandates
The timeline of SLR adjustments reflects the shifting priorities of the Indian economy. In , the rate was moved from 34% to 35% across two distinct phases. By , the requirement was hiked to 37.5% of net demand and time liabilities. Following a surge in reserve money and a decline in food credit in , the rate reached a significant 38% on , to moderate excess liquidity.
- (i) In , incremental SLR for new liabilities was reduced from 30% to 25%.
- (ii) On , a uniform valuation system for SLR securities was implemented.
- (iii) By , NRE account SLR was rationalized from 30% to 25%.
Finally, on , a uniform SLR of 25% was established for all scheduled commercial banks, aligning with the minimum requirements of Section 24 of the Banking Regulation Act, 1949. Today, the current SLR rate stands at 18%.
Important Historical Verification: Please note that older corporate finance listings or previous drafts specifying the modern SLR rate as 24% are outdated. Under modern RBI parameters, the ratio has been systematically lowered to 18% to expand commercial credit pathways.
Evaluate the Strategic Objectives and Macroeconomic Impact
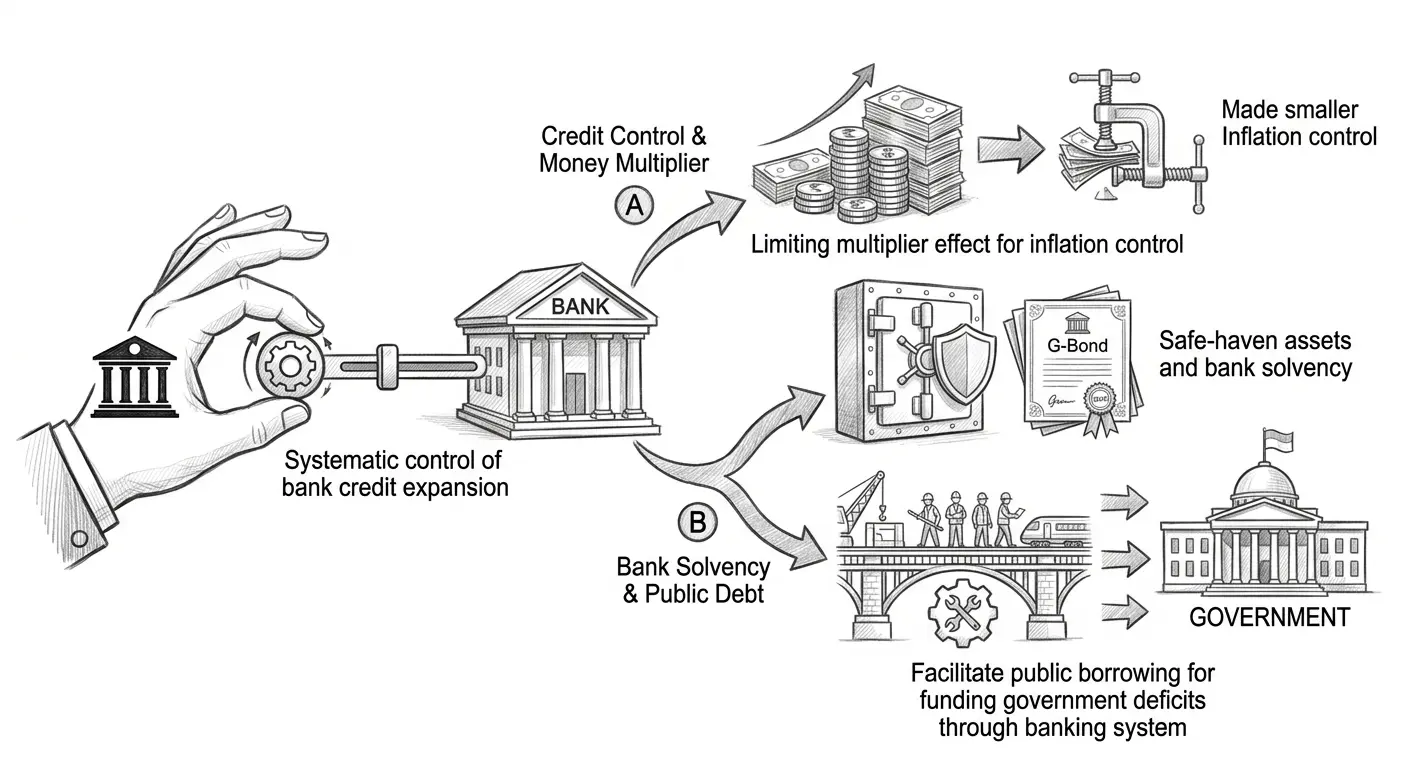
The overarching goal of the SLR policy is the systematic control of bank credit expansion. By modulating the required holdings of liquid assets, the RBI maintains a firm grip on credit creation.
Assessing Credit Control, Bank Solvency, and Public Debt
The primary impact of SLR is threefold. First, it acts as a tool for inflation control by limiting the money multiplier effect of banks. Second, it guarantees bank solvency by forcing institutions to hold safe-haven assets like government bonds. Third, it facilitates public borrowing, ensuring that the government can fund its deficits through the banking system at stable interest rates. During periods of high inflation, the RBI strategically raises the ratio to safeguard depositors' funds and curb excessive liquidity.
⚡ Quick Revision Capsule: Statutory Liquidity Ratio (SLR)
Key parameters and comparison points regarding Statutory Liquidity Ratio in India:
| Feature / Metric | Statutory Liquidity Ratio (SLR) | Cash Reserve Ratio (CRR) |
|---|---|---|
| Primary Custodian | Maintained internally by commercial banks within their own vaults. | Deposited directly with the Reserve Bank of India (RBI). |
| Approved Asset Forms | Physical cash, valued holdings of gold, and unencumbered government securities. | Maintained strictly in the form of liquid cash balances. |
| Interest Returns | Banks earn interest yield on holdings like government bonds. | No interest yield is paid by the RBI on CRR balances. |
| Historical Peak Level | Reached a record cap of 38% on . | Adjusted periodically alongside monetary expansion goals. |
| Governing Statute | Regulated under Section 24 of the Banking Regulation Act, 1949. | Regulated under Section 42(1) of the Reserve Bank of India Act, 1934. |
📝 Summary
The Statutory Liquidity Ratio (SLR) remains a fundamental pillar of India's banking architecture. From its peak levels in the to the streamlined 25% mandate established in , the policy has successfully balanced the need for bank safety with the requirements of government fiscal policy. While it necessitates a reduction in commercial lending, the trade-off provides a stable environment for long-term economic growth and protects the financial integrity of the nation’s banking institutions against sudden liquidity shocks.
🚀 Quick Revision Points
Essential facts to review before examinations:
- (i) The SLR is maintained by commercial banks within their own vaults in cash, gold, or approved securities, unlike the CRR which goes to the RBI.
- (ii) The ratio reached its historic peak of 38% in to counter excess liquidity spikes.
- (iii) Financial reforms in established a uniform floor rate of 25% under Section 24 of the Banking Regulation Act, 1949.
- (iv) In contemporary banking operations, the modern adjusted baseline rate stands at 18%.
- 💡 Exam Tip: Remember that SLR holdings earn interest returns for banks via government securities, whereas CRR deposits kept with the RBI yield zero interest.
❓ Frequently Asked Questions (FAQ)
Q1: What are the eligible asset forms for fulfilling SLR mandates?
A1: Banks can park their funds in physical cash, valued holdings of gold, and government-approved unencumbered securities to fulfill statutory requirements.Q2: How did the SLR change during the peak stabilization era of 1987-1988?
A2: The ratio was adjusted upward from 37.5% in to a record cap of 38% on , driven by the need to balance an expanding reserve money profile.Q3: Where are SLR funds held compared to CRR reserves?
A3: SLR holdings are kept internally by the commercial banks themselves and can earn interest via coupon securities. Conversely, CRR holdings are cash deposits placed with the Reserve Bank of India that earn zero interest return yield metrics.