The Monetary Targeting framework in India serves as the cornerstone of macroeconomic stability, acting as a deliberate choice over pure interest rate models found in more developed economies. Historically, this policy evolution reflects India's unique financial setup, where the Reserve Bank of India (RBI) prioritizes managing Broad Money (M3) to control inflationary pressures and support economic growth. Understanding why India targets money supply over the cost of credit provides valuable insight into the sovereign economic management of an emerging market as its financial sector grows.
🎯 In this chapter, you will understand:
- The structural reasons why India prefers monetary targeting over interest rate policy.
- How financial market fragmentation limits interest rate transmission.
- The mechanics of flexible monetary targeting and intermediate targets.
- The operational link connecting Reserve Money, M3, and overnight call rates.
💡 Why this topic matters: Central bank choices on money supply directly impact price stability, credit availability, and long-term national growth.
🧠 Core Idea: India regulates the total volume of money directly because incomplete market integration makes simple interest rate signals less reliable.
Comparing Monetary Targeting and Interest Rate Policy
In economic study, the primary alternative to monetary targeting is using the interest rate as the central policy tool. While setting interest rates is common in advanced economies, its success depends on having different parts of the financial markets—like stocks, bonds, and currencies—seamlessly integrated. When these markets are linked well, a change in one interest rate spreads effectively through the others, influencing the entire economic ecosystem.
Limitations of Interest Rate Policy in India
Moving from theory to practice, India faces structural hurdles that prevent full reliance on interest rate signaling. The policy transmission mechanism is often slowed down because markets are divided into separate segments.
- (i) Fragmented markets lead to inefficient interest rate transmission.
- (ii) Direct targeting of monetary aggregates provides a more reliable anchor for inflation control.
Evaluate Financial Market Integration and its Constraints
In India, financial market integration has not reached complete alignment, despite positive trends and gradual improvements. Because monetary authorities cannot guarantee that a rate change will affect all sectors equally, targeting the money supply is more effective. This approach regulates the actual volume of money in circulation, while officials continue watching interest rate movements and stepping in as needed to keep liquidity smooth.
Flexible Monetary Targeting in India
The Reserve Bank does not follow a rigid formula. Instead, it practices flexible monetary targeting. This adaptive approach allows for regular adjustments based on real economic conditions and global economic developments.
- Flexible policy design lets the central bank respond dynamically to unexpected domestic and international shocks.
Strategic Advantages of Intermediate Targets
Choosing monetary aggregates as intermediate targets rests on two functional strengths in India. First, the money demand function has shown strong stability over time, helping the central bank forecast price movements accurately. Second, a clear money stock target acts as an effective communication tool, giving businesses and market participants an unambiguous signal about the government's monetary policy stance.
Emerging Trends in Policy Implementation
As India's economy grows, the monetary authorities have expanded their strategy. While Broad Money (M3) remains a central intermediate target, execution is now multi-dimensional, bringing in a wider range of economic indicators for better accuracy.
- Policy adjustments now blend traditional monetary benchmarks with real-time liquidity indicators.
The Operational Chain: From Reserve Money to Call Rates
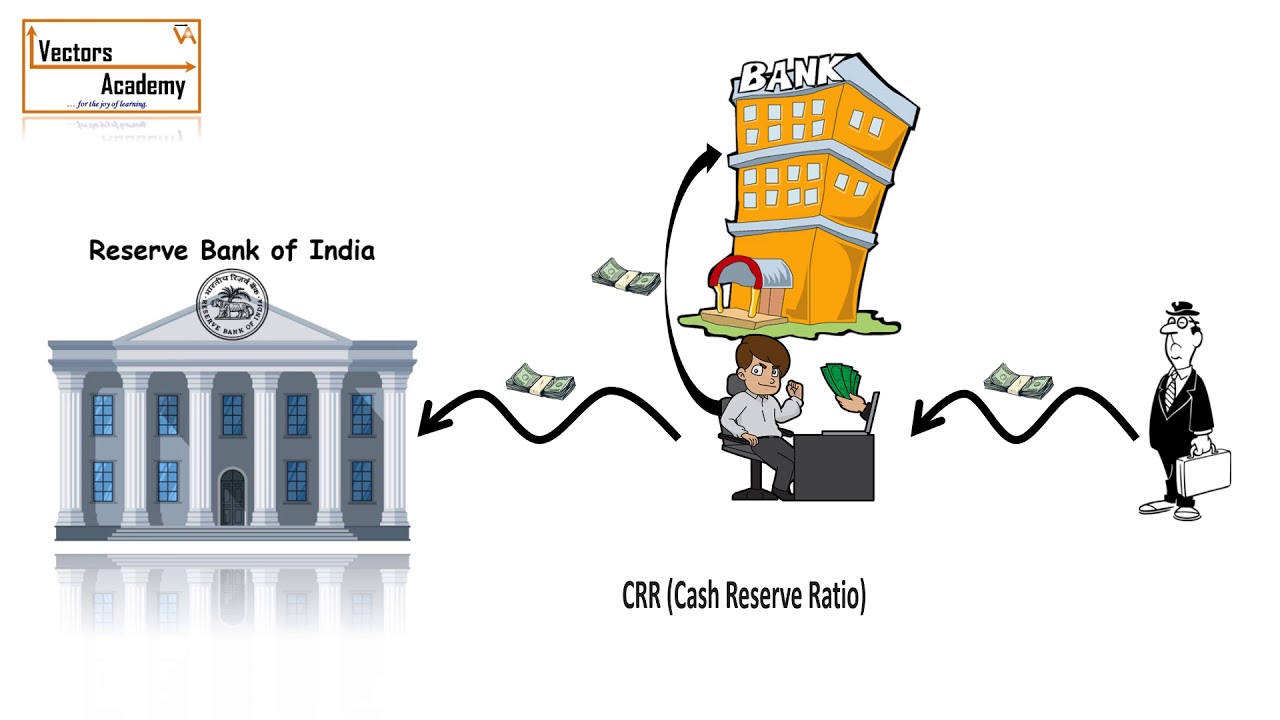
To reach target levels for broad money, the RBI focuses on its operational target: reserve money, especially bank reserves kept by commercial banks. This is refined by a supplementary operating target known as the short-term interest rate. In India, this is best seen in overnight call money rates, which act as a barometer for immediate liquidity across banks.
Operational Chain from Bank Reserves to Call Money Rates - Broad Money (M3): The main intermediate target used to guide long-term inflation and economic growth goals.
- Reserve Money: The primary operational target controlled directly through central bank reserves and operations.
- Overnight Call Rates: A supplementary operating target showing daily liquidity conditions in the commercial banking sector.
- Financial Integration: The degree to which different financial sectors move together in response to central rate changes.
⚡ Quick Revision Capsule: Indian Monetary Targets
A structured comparison of the target levels and policy mechanisms used by the Reserve Bank of India:
| Policy Target Level | Primary Instrument / Aggregate | Core Function & Economic Purpose |
|---|---|---|
| Intermediate Target | Broad Money (M3) | Anchors overall price stability and controls long-term inflation. |
| Operational Target | Reserve Money (Bank Reserves) | Directly managed by RBI to control the total volume of money supply. |
| Supplementary Target | Overnight Call Money Rates | Provides immediate signals on short-term liquidity within banks. |
| Structural Policy | Flexible Monetary Targeting | Adapts targets based on domestic feedback and global trends. |
| Policy Foundation | Money Demand Function | Offers a stable base to predict prices and guide market expectations. |
📝 Summary
The Indian Monetary Framework balances traditional money supply targets with modern market indicators. By using flexible monetary targeting, monetary authorities rely on a stable money demand function to keep prices steady while guiding reserve money through overnight call money rates. While an pure interest rate policy remains a long-term goal that requires deeper market integration, targeting the money supply remains the most effective safeguard for India's economic stability and clarity.
🚀 Quick Revision Points
Essential facts to review before examinations:
- (i) Advanced economies use interest rate policy because their financial markets are fully integrated.
- (ii) The RBI relies on flexible monetary targeting because India's money demand function is stable.
- (iii) The key intermediate goal is Broad Money (M3), while Reserve Money is the primary operational lever.
- (iv) Overnight call money rates act as a short-term indicator to measure daily banking liquidity.
- 💡 Exam Tip: Remember the clear order of targets: Reserve Money is operational, M3 is intermediate, and call rates act as the daily liquidity gauge.
❓ Frequently Asked Questions (FAQ)
Q1: Why doesn't India completely replace monetary targeting with interest rate targeting?
A1: Full interest rate policy requires fully integrated financial markets. Because connections between Indian market segments are still growing, regulating money supply gives a more reliable way to manage inflation.Q2: What is the relationship between M3 and Reserve Money in operations?
A2: Broad Money (M3) is the intermediate target affecting inflation, while Reserve Money is the direct operational target managed through central bank operations.Q3: How do overnight call money rates figure into the strategy?
A3: They serve as a supplementary operating target, offering a quick reading of liquidity conditions across commercial banks.